A paid gift-packaging option covers its modeled service costs when uptake produces enough contribution to recover preparation. Separate the fee from per-use materials and work, then calculate the number of selected gift orders needed. Total store orders alone do not measure gift-service demand.
Define the paid service before pricing it
Specify whether the option includes a presentation box, wrapping, a message or another named arrangement. State whether buyers choose it per order, per item or per gift unit. Your actual platform and service terms control that basis.
The gift-ready fulfilment guide connects checkout information with the physical pack. A cost model adds the materials and work required each time that defined service is selected.
Keep ordinary packing costs separate from added gift work. If every order already receives a box, don’t charge its full cost as an additional gift component unless the paid option actually replaces it with a different arrangement.
A 12-percent crossing under assumed inputs
Suppose a fictional period has 1,000 orders. The gift fee is $4, service-specific materials and labor cost $2.50 per use, and preparation costs $180 for the period. All amounts are invented USD inputs; taxes, payment fees and other costs are excluded.
The contribution is $4 minus $2.50, or $1.50 per selected gift order. Dividing $180 by $1.50 gives 120 selections, equal to 12 percent of the assumed 1,000 orders.
Scroll horizontally if columns extend beyond the view.
| Gift selections | Assumed uptake | Contribution before preparation | After $180 preparation |
|---|---|---|---|
| 80 | 8% | $120 | Negative $60 |
| 120 | 12% | $180 | $0 |
| 200 | 20% | $300 | $120 |
The table does not forecast what customers will choose. It identifies the uptake at which these particular included costs are covered.
Keep purchased stock outside the consumption shortcut
The per-use material figure describes consumption in this model. An actual purchase may require more gift boxes than the period uses. Show that initial cash and leftover count in a separate procurement scenario rather than pretending the purchase equals only selected orders.
Similarly, a message reprint, a different box size or a special ribbon can create additional work. Record the actual exception cost and frequency if known. Don’t assume every gift order follows the same operation without testing the service definition.
If the contribution per use is zero or negative, more uptake won’t recover the fixed preparation amount under that pricing scope. Changing the service, fee or cost inputs is a separate decision, not an outcome the model can guarantee.
Trial the service and revisit the assumptions
Run a defined packing trial for the proposed gift arrangement and identify its recurring materials. After launch, compare recorded selections with the modeled uptake cases and preserve any changed operation. The output should be a clear service definition, a purchase-cash plan and a period cost-coverage range, with each assumption visible.
Sources and scope
Australian Government supports the stated general concepts within this scope: Cash inflows/outflows and clear labeling of estimated figures. Access checked 14 October 2026.
The worked scenario is original editorial analysis with assumed inputs, not a supplier offer, customer record or measured Packrivo result. Commercial feasibility and physical suitability remain project-specific.
Retain the service denominator beside its cost rows
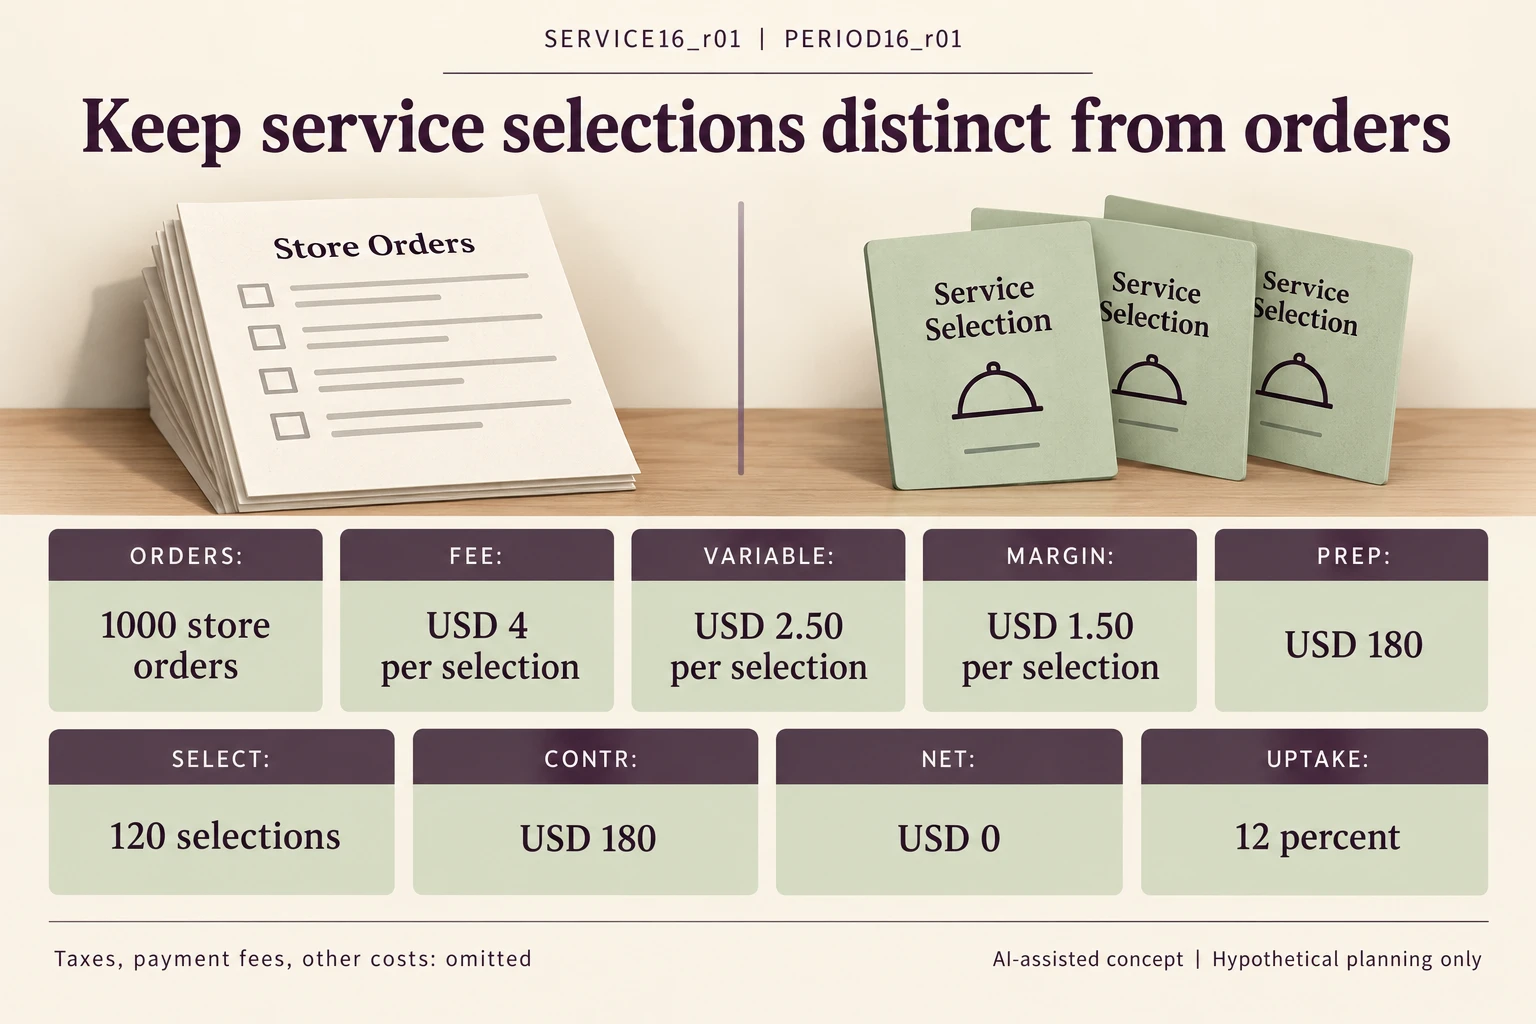
The original 120-selection crossing becomes a scoped register for SERVICE16_r01 and PERIOD16_r01. One selection means one selected gift order. The fictional period contains 1,000 store orders; its service-specific fee and recurring cost are $4 and $2.50 per selection.
Scroll horizontally if columns extend beyond the view.
| Scope ID | Exact entity | Stage / role | Hypothetical basis |
|---|---|---|---|
| ORDERS | PERIOD16_r01 | INPUT | Assumed period denominator |
| FEE | SERVICE16_r01 | INPUT | USD4 per selected gift order |
| VARIABLE | SERVICE16_r01 | INPUT | USD2.50 material and labour per selection |
| MARGIN | SERVICE16_r01 | CALCULATION | 4 – 2.50 |
| PREP | PERIOD16_r01 | INPUT | Period preparation USD180 |
| SELECT | SERVICE16_r01 | INPUT | Assumed selected gift orders; not all store orders |
| CONTR | PERIOD16_r01 | CALCULATION | 120 x 1.50 |
| NET | PERIOD16_r01 | CALCULATION | 180 – 180 |
| CROSS | PERIOD16_r01 | CALCULATION | 180 / 1.50 |
| UPTAKE | PERIOD16_r01 | CALCULATION | 120 / 1000 x 100 |
MARGIN is $1.50 per selection, CONTR is 120×$1.50=$180, and NET after $180 preparation is zero. UPTAKE is 120/1,000×100=12%. CROSS separately records 180/1.50=120 selections. Each input and calculation has its own row so total store orders cannot silently become service selections.
This is cost coverage for the stated included work, not net profit or predicted customer uptake. Taxes, payment fees and other costs are omitted. Actual selections and cost evidence remain blank. The register does not turn consumed material cost into a purchase-cash claim.
Download the paid gift wrapping pricing record (.csv). HYPOTHETICAL rows are invented examples. Use ACTUAL_BLANK for permitted project inputs; replace that row label only when recording actual facts. Empty evidence, observation and date fields mean unknown or not performed, never acceptance. Keep checkpoints and revisions separate.
Use the named scope rows and unresolved evidence to prepare a project enquiry. Replace planning assumptions with actual authorised records before a commercial or use decision. Packrivo coordinates independent suppliers. These records establish no supplier offer, service availability or MOQ exception; its published baseline is 500 pieces per product/design.